
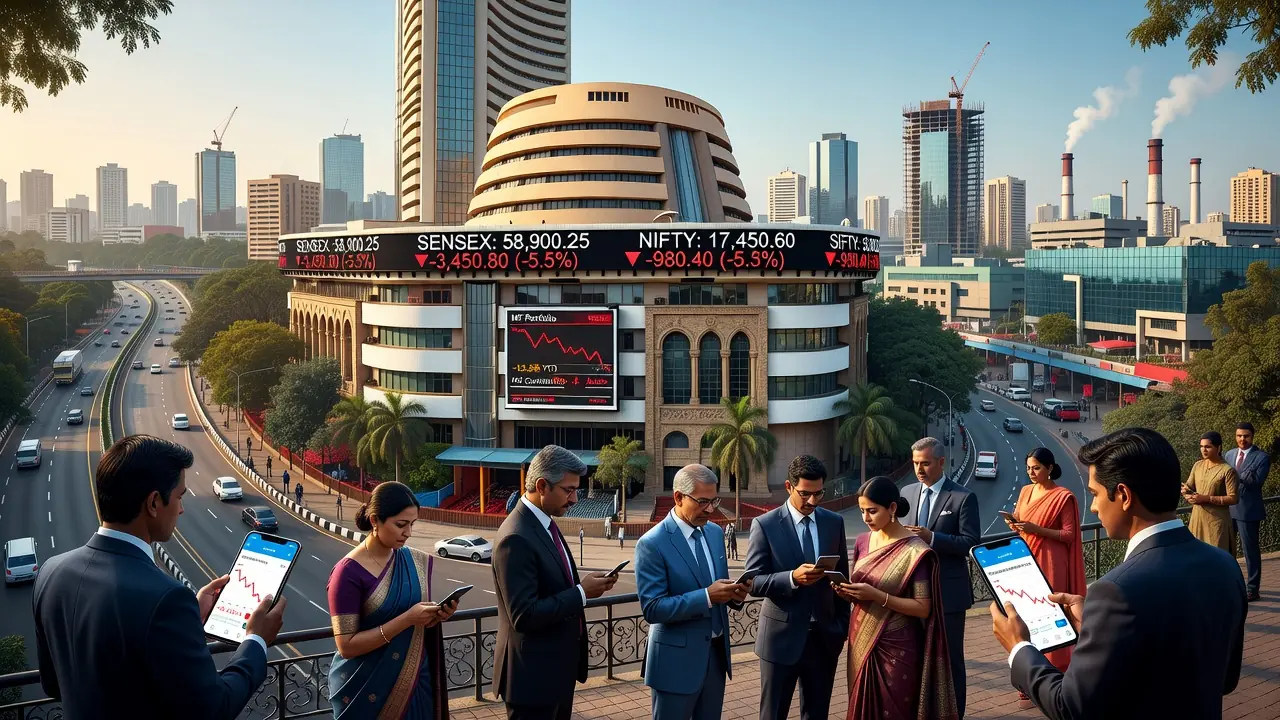
An economy expanding at more than 7% a year would normally be expected to power a rising stock market. India is defying that logic. Its benchmark Sensex and Nifty indices have just ended the longest run of weekly losses in a quarter-century, leaving ordinary investors nursing double-digit losses even as the headline growth numbers remain the envy of the world.
A growth story that isn't translating into returns
The disconnect is stark when set against other major markets. Indian retail investors who put money into the Nifty this year have seen roughly 15% of their wealth wiped out, while investors in South Korea's Kospi have enjoyed far stronger gains over the same period and over the past two years. Foreign institutional investors have been pulling money out steadily, and the cumulative net inflow into Indian equities over the past decade is now close to zero once withdrawals are accounted for. What has kept the market from falling further is domestic money - a large and growing base of mutual fund investors and retail savers who have continued to invest even as returns have soured.
External shocks meeting structural weaknesses
Several forces are compounding each other. Prolonged disruption to shipping through the Strait of Hormuz has kept crude oil prices elevated for months longer than markets expected, and India imports the overwhelming majority of its oil needs. Higher crude prices feed directly into inflation and squeeze corporate margins, a dynamic fund managers say markets can tolerate only up to a point before sentiment turns sharply negative. At the same time, rising global interest rates - with US government bond yields near multi-decade highs - have made safer, developed-market assets more attractive relative to emerging-market equities, encouraging capital to flow out of markets like India's. A weaker rupee has made the problem worse for foreign investors, since currency losses erode returns that were already underwhelming in dollar terms.
Valuations, technology, and the missing growth engine
Indian equities have become cheaper relative to their own history, but they remain expensive compared with regional peers once earnings are factored in. Part of the gap reflects a structural issue: markets such as South Korea and Taiwan have benefited from a surge in corporate profits tied to artificial intelligence infrastructure, while India has yet to produce a globally significant AI company. Analysts note that many of the country's largest listed firms are concentrated in established, protected sectors rather than emerging technology, limiting their appeal to foreign funds chasing growth themes. Smaller Indian companies working in areas such as semiconductors, space and defence technology are seen as promising, but most are still too small to shift capital allocation decisions in a meaningful way.
What happens next
Corporate earnings reports due in the coming weeks will offer the clearest picture yet of how much margin pressure companies are actually absorbing from higher energy costs and currency weakness. Analysts suggest that easing geopolitical tensions and relatively attractive valuations could eventually draw foreign capital back, but trade tensions and elevated energy prices remain genuine risks to corporate performance. For now, the resilience of domestic retail investors - who have continued their monthly mutual fund contributions despite falling markets - has been the main stabilising force. Whether that discipline holds if losses deepen further is the question now facing India's financial system, and one with consequences well beyond the stock market itself.